London · UK mortgages · International perspective

Finance for the life
you’re building.

A UK home mortgage, an international & overseas property purchase or a conversation in the room: choose your purpose. Start with the facts, understand the process and define the next step.

Choose your path below ↓
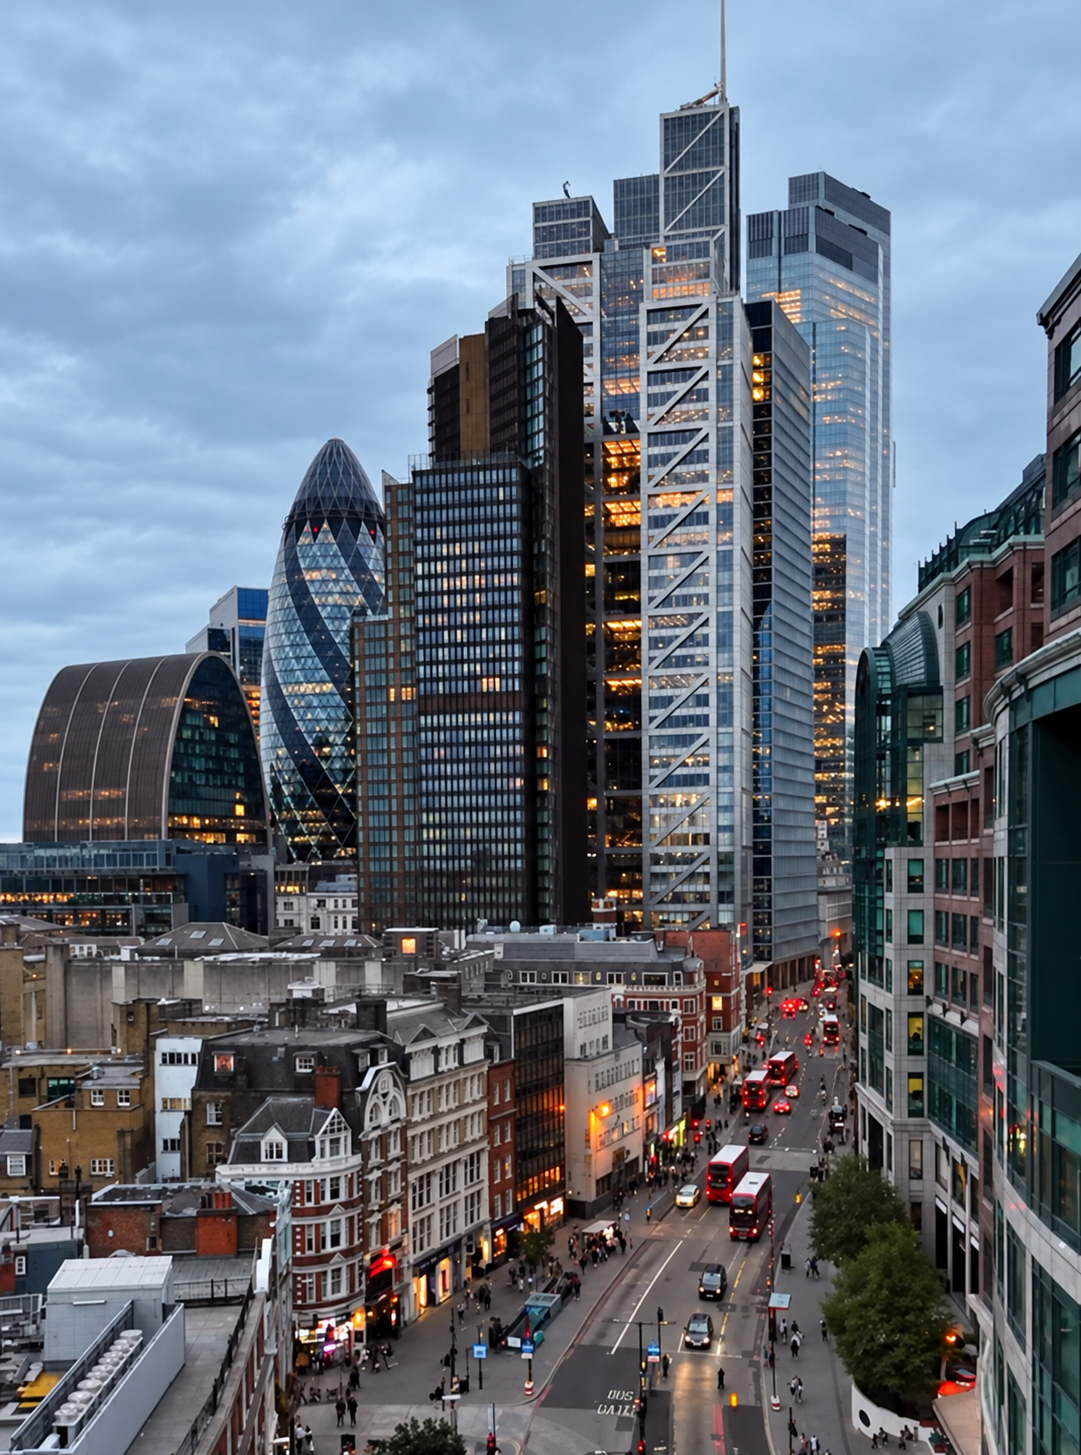
City of London skyline with clustered towers, the Gherkin and a street in the foreground
51.5072° NLondon perspective

Choose your starting point

Three paths.
One clear next step.

Follow the route that fits your purpose. The tools and explanations stay with the topic.

01 · Mortgages

Your home.
A considered mortgage.

Start with the circumstances. Understand the process. Then explore the figures.

01

UK MORTGAGES

Structure before product.

For first-time buyers, home movers, remortgages and buy-to-let. We begin with your income, commitments, deposit and property before comparing lenders and products.

  • Affordability and monthly payment
  • Deposit, equity and LTV
  • Criteria and documentation
5% deposit. A closer look.

A 5% deposit does not automatically secure a 95% mortgage. The loan-to-value ratio describes the borrowing relative to the property value; it does not measure affordability or confirm eligibility.

In Q2 2026, lending above 90% LTV accounted for 8.4% of the value of gross mortgage advances — the highest share since Q2 2008. This covers lending above 90%, not just 95% mortgages.

What sits behind the decision?

  • Income: how it is earned, evidenced and accepted by the lender.
  • Commitments and credit history: existing repayments, spending and the credit profile.
  • Property and term: valuation, property type and the proposed repayment period.
  • Affordability and lender criteria: whether the proposed borrowing fits both your budget and the lender’s rules.

Two buyers with the same headline income, deposit and purchase price can receive different answers. Variable pay, self-employed income, existing commitments or the property itself can change the assessment.

That is why the starting point is your circumstances and evidence. Then comes lender selection, followed by a comparison of rates, fees and suitability. A different lender may assess a case differently; approval is never guaranteed.

Source: FCA / PRA · Q2 2026 · Published 8 September 2026

All mortgages are subject to status, affordability and lender criteria. Your home may be repossessed if you do not keep up repayments on your mortgage.

Talk about a mortgage
Residential street in London

YOUR ROUTE TO A HOME

A clearer path. A calmer next step.

From the first conversation to collecting your keys: explore seven stages at your own pace.

A disciplined route

Know what happens next.

The process should reduce uncertainty, not add to it.

Four priorities. Seven stages to explore — select a card to look closer.

Interactive planning tools

Your figures. A clearer starting point.

Explore monthly payments, deposit and LTV, or compare two remortgage scenarios including fees.

Open the calculators

UK Property Finance · Investment perspective

From a home.
To a property strategy.

Rental property, a refurbishment or a commercial asset: the purpose changes the financing route. Start with the project, its cash flow and how the borrowing will be repaid.

01

Hold · Let · Review

Buy-to-let

UK rental property as an investment. Look beyond the headline rent to financing, running costs and periods without tenants.

02

Acquire · Improve · Exit

Bridging & Development

Short-term acquisition or refurbishment, and a separate route for construction. Match the funding to the works and a credible repayment plan.

03

Use · Transform · Refinance

Commercial & Conversions

Business premises, investment assets and mixed-use property. A conversion needs its own assessment of works, permissions and the final use.

An educational overview of financing routes. Availability and the advice or referral pathway will be confirmed within the approved service scope. No finance or investment return is guaranteed.

Property used as security may be repossessed if you do not keep up repayments on borrowing secured against it.

Coastal residential buildings and palm trees beneath the mountains in Marbella, Spain
Property is specific. The questions should be too.

International & overseas property perspective

Opportunity deserves
due diligence.

Explore international & overseas property for personal use, rental income or a mix of both. Start with the purpose, understand the local market and check the project before committing.

Strategies, partner management and five questions worth asking.

How introductions work

Clear roles.
A documented introduction.

We help open the right conversation and coordinate relevant contacts. Before an introduction, clarify the purpose, the partner’s role and which information may be shared.

  1. Your objective
  2. Agreed scope
  3. Partner introduction

Within International & Overseas Property

For developers and agencies.

Clear responsibilities, documented introductions and agreed commercial terms are the foundations of a working partnership.

03

DEVELOPER & PARTNER COLLABORATION

Build a documented relationship.

For developers, agencies and professional partners: establish the offer, responsibilities and client introduction process before working together.

  • Define the offer and audience
  • Agree roles and introduction evidence
  • Document commercial terms
Discuss a partnership

M&I Invest Interactive

A weekend for better questions.

Explore the proposed two-day property and finance event. Date to be confirmed. Venue, speakers and programme will be announced after arrangements are confirmed.

Explore the event

M&I Market Chronicle

The market.
Made understandable.

Short market notes and practical guides. Facts, context and a useful next question.

Read the Chronicle

Marcin Grzelak · London

Direct conversation.
Clear reasoning.
Visible next step.

For nearly two decades in the UK, Marcin’s work and network have developed around finance, property and the decisions connecting them.

The approach is personal but disciplined: understand the objective, separate facts from assumptions, explain the trade-offs and document what needs to happen next.

Begin with your objective
Marcin Grzelak
“Clarity is not having every answer. It is knowing which question comes next.”

The M&I perspective

The right decision is not the one with the loudest headline. It is the one that still makes sense when the rate, fees, criteria and longer-term plan are viewed together.

Your next move

Start with the
right conversation.

Choose a topic to open the form. A short outline is enough: no identity documents or detailed financial information.

We welcome mortgage enquiries and requests to start the application process. M&I works with a network of contacts and specialists across the UK and internationally. Formal mortgage applications and personalised advice are handled by appropriately authorised firms and advisers within their service scope. We confirm the responsible specialist and next steps before a referral; please do not send financial documents through this website.

CONNECT · COLLABORATE · CREATE OPPORTUNITIES

Bring together knowledge, people and the right next step.

International & overseas property perspective

Opportunity deserves
due diligence.

An introduction is not a recommendation. Before committing, understand the developer, ownership structure, local market, all costs, currency exposure and what happens if the plan changes.

M&I can open the conversation and coordinate relevant contacts. Legal, tax and investment decisions stay with appropriately qualified professionals.

One property. Different purposes.

Personal useRental investmentMixed use

International ownership. Management on the ground.

Selected projects offer partner-managed short-term or long-term letting. Availability and scope depend on the project, contract and local rules. Before buying, establish who runs the service, what they charge and which responsibilities remain with the owner.

Compare income after costs, owner responsibilities and contract exit terms. Management does not guarantee occupancy or returns.

Open a question to see what to check and how to frame your own answer.

What exactly am I buying?

Check the legal title, what is included and whether ownership can be transferred. Distinguish a completed home from an off-plan commitment or a share in a structure.

Your answer should sound something like:

I can describe what I will own, how I may use it and which documents confirm this.

What evidence supports the proposition?

Ask for verifiable documents, completed projects and comparable local transactions. Separate observed results from forecasts and check the assumptions behind rental projections.

Your answer should sound something like:

I know which figures are documented, which are estimates and what still needs independent checking.

Which local rules apply to my plan?

Have an independent local lawyer check buyer eligibility, ownership restrictions, permissions and letting rules. Ask a qualified tax adviser about local and home-country obligations; do not assume a purchase grants residency.

Your answer should sound something like:

My intended use has been checked for this location and my circumstances before I commit.

Does the location fit real life?

Look beyond the view: transport, services, seasonal demand, language and local customs. For letting, check the operator, guest or tenant support, maintenance and reporting. The scope of service should be set out in the contract, not just a presentation.

Your answer should sound something like:

This location fits my purpose and I know who will handle day-to-day matters.

Can I carry the costs if the plan changes?

Budget for purchase, running costs, tax, finance, currency movements and management fees. Assess rental income after costs. Allow for vacancy, delays and a slower resale; check cancellation terms and your cash reserve.

Your answer should sound something like:

I have a reserve and a realistic exit plan that do not rely on a promised return.

A starting point for discussion. The detail depends on the country, property and your circumstances.

GOV.UK practical guide: buying property abroad
Before we talk: your property brief

Outline the country or location, purpose, total budget, funding approach, timing and how involved you want to be. If rental is part of the plan, identify short- or long-term letting and the costs and services you expect a local manager to cover.

Does management mean guaranteed rental income?

No. Check the operator, contract, fees, maintenance, reporting, local letting requirements and vacancy assumptions. Management is a service; it does not remove investment risk.

Who handles the purchase and who handles the rental?

An introduction connects you with a relevant partner. The seller or developer, independent legal and tax advisers, and any management operator have separate responsibilities. Confirm each role, scope and contract before committing.
Before we talk: a short checklist

Have an outline of your goal, property budget, deposit, timing, income structure and regular commitments. For remortgage, note your current deal end date and any early repayment charge. Approximate figures are enough for an initial conversation. Keep documents for an agreed secure channel.

Mortgage questions, explained simply

Does a deposit mean I can get a mortgage?

It is one part of the picture. A lender also assesses affordability, evidence, credit history and the property. An LTV calculation does not confirm eligibility.

Is an agreement in principle a final offer?

No. It is an initial indication based on information assessed at that stage. A formal application, further checks and property assessment may still be needed.

Is the lowest rate always the best fit?

Compare fees, term, deal period, flexibility and early repayment charges alongside the rate. A lower monthly payment can also reflect a longer repayment period. The adviser assesses suitability through the approved process.

What documents might I need?

Proof of identity, income, deposit and regular spending is commonly requested. The exact list depends on your employment and the lender. Use the agreed secure channel; do not send financial documents through a general enquiry form.

Can I apply if I am self-employed?

Self-employment does not automatically rule out a mortgage. The lender needs evidence of your income, which can include accounts and tax records. How income is assessed and how much history is required vary by lender and business structure.

Does credit history affect the decision?

Lenders review your credit history alongside affordability. Explain missed payments or other issues accurately so the case can be assessed against the relevant criteria. A headline credit score alone does not confirm mortgage eligibility.

What should I budget for beyond the deposit?

Allow for legal work, a survey, applicable property tax, mortgage or adviser fees where charged, and moving costs. Confirm which fees apply and when they are payable. Keep a separate reserve for unexpected costs rather than committing every pound to the deposit.

Is the lender’s valuation the same as a survey?

No. A mortgage valuation supports the lender’s decision about the property’s value. A separate survey examines its condition and can identify problems or repairs. Discuss the appropriate survey with a qualified surveyor; a valuation is not a substitute.

What should I check before my current deal ends?

Check the deal end date, outstanding balance, remaining term and any early repayment charge. Compare a product transfer with your current lender and a remortgage to another lender, including fees and total cost. Allow time for the checks and avoid assuming that a lower rate guarantees a saving.

General guidance. The requirements and options depend on your circumstances and the lender; this is not an individual recommendation.

Before we talk: your property brief

Outline the country or location, purpose, total budget, funding approach, timing and how involved you want to be. If rental is part of the plan, identify short- or long-term letting and the costs and services you expect a local manager to cover.

Different risks. Different protection.

The right questions start with your household, commitments, existing cover and budget. These are distinct types of insurance, with different conditions and purposes.

01 · Buildings & contents: what is the difference?

Buildings insurance covers the structure and permanent fixtures against insured risks; contents insurance covers belongings. Mortgage conditions usually require buildings cover. Check the required start date with your lender and legal representative. For a leasehold property, confirm whether a block policy is already arranged and what it covers.

02 · Life & critical illness: what do they address?

Life insurance can provide a payment if the insured person dies during the covered period, subject to the policy. Critical illness cover can pay for a diagnosis that meets a specified condition and its definition. They are not interchangeable. Check the amount, term, exclusions and whether a combined policy ends after a claim.

03 · Income protection: what should I check?

Income protection can replace part of your income if illness or injury prevents you from working, subject to the policy. Check the definition of being unable to work, the waiting period and how long payments can continue. Compare this with employer sick pay, existing benefits and savings. Do not assume it covers redundancy.

Before choosing: five things worth checking

What is already covered? Which risks remain? What must happen for a claim to be paid? What costs, limits and exclusions apply? Can you sustain the premiums over time? Answer application questions accurately and review the cover when your home, family or work circumstances change.

Educational information, not a personal insurance recommendation or an offer to arrange cover. Eligibility, premiums and claims depend on the insurer and policy terms. Individual advice should come through an appropriately authorised adviser.

Further reading · MoneyHelper

Buy-to-let

What changes when the property is for rent?

A buy-to-let mortgage finances a rental property. Lenders assess the expected rent, borrowing and their own criteria. Interest-only borrowing leaves the capital to be repaid separately. If you plan to let a home with a residential mortgage, check the lender’s consent or the appropriate mortgage route first.

What should the investment calculation include?

Allow for finance costs, management, maintenance, insurance, tax and vacancy. Rental income and future property values can change. Review the ownership structure with a qualified tax adviser and verify the relevant local letting requirements before committing.

Prepare your project brief

Location, purchase price or current value, deposit or equity, realistic rent, running costs, ownership structure and any existing portfolio.

An educational overview of financing routes. Availability and the advice or referral pathway will be confirmed within the approved service scope. No finance or investment return is guaranteed.

Property used as security may be repossessed if you do not keep up repayments on borrowing secured against it.

Further reading

Bridging & Development

Bridging: what is the role of the exit?

Bridging is short-term secured finance that can support a purchase or suitable refurbishment. Its exit is how you intend to repay, such as sale or refinancing. Check the total interest, fees and term, and what happens if the sale, works or refinancing are delayed. An intended refinance is not an approval.

When does development finance become relevant?

Ground-up construction and major works can require development finance rather than a simple bridge. Funding may be released in stages against progress. The assessment considers the project budget, permissions, experience and expected completed value. Build in contingency for cost increases and delays.

Prepare your project brief

Property or site details, acquisition cost, scope of works, permissions status, cost schedule, cash contribution, experience, timetable and repayment plan.

An educational overview of financing routes. Availability and the advice or referral pathway will be confirmed within the approved service scope. No finance or investment return is guaranteed.

Property used as security may be repossessed if you do not keep up repayments on borrowing secured against it.

Further reading

Commercial & Conversions

Commercial mortgage: business use or investment?

Commercial mortgages can support premises used by a business or property held for commercial rental income. Mixed-use assets combine uses, such as a shop with flats above. The assessment depends on the asset, borrower, business or rental cash flow, leases and lender criteria.

Does a commercial mortgage fund a conversion?

Not automatically. Converting an office or shop into homes can need acquisition finance, refurbishment or development funding, then a separate long-term exit. Check the planning position and required approvals with qualified professionals. The finished property and its use influence the eventual mortgage route.

Prepare your project brief

Current and proposed use, property details, purchase or refinance amount, occupancy and leases, business or rental cash flow, planned works and permissions.

An educational overview of financing routes. Availability and the advice or referral pathway will be confirmed within the approved service scope. No finance or investment return is guaranteed.

Property used as security may be repossessed if you do not keep up repayments on borrowing secured against it.

Further reading

How introductions work

From first conversation to clear responsibilities.

A practical framework for a property introduction. The detail depends on the country, project and parties involved; agreed responsibilities should be recorded before you commit.

Define the objective

Outline the location, intended use, overall budget, funding approach and timing. A first enquiry needs a short brief, not identity documents, bank statements or confidential financial records.

Understand the partner and proposition

Establish whether you are dealing with the developer, an agency, a finance specialist or a management operator. Ask for the relevant documents, completed-project evidence, ownership terms and the person responsible for each part. An introduction is a starting point for checks, not a guarantee of the project.

Agree the information to be shared

Before a requested introduction, identify the recipient, purpose and minimum details needed. An enquiry does not itself authorise partner marketing. The recipient should explain its own privacy practices. Any wider mailing subscription is a separate choice.

Make fees and interests transparent

Clarify whether M&I or another party may receive an introduction fee or commission, who pays it and the amount or basis where relevant. Identify any charges payable by you and potential conflicts of interest. Document the applicable commercial terms before a commitment; do not assume the service is free.

Separate the roles before proceeding

M&I can facilitate introductions and coordinate the conversation. The seller handles its offer and sale contract; independent qualified professionals handle legal and tax advice. Personal mortgage recommendations require a separate authorised advice process. Check any management operator’s fees, reporting, owner duties and exit terms in its own agreement.

Record the next step and verify independently

Keep a written record of the introduction, the partner’s acknowledgement, responsibilities and next action. Before reserving or buying, independently check title, permissions, local restrictions, total costs, currency exposure and cancellation terms. Test rental assumptions after management fees, running costs and vacancies.

An introduction is not a personal investment recommendation or a guarantee of financing, ownership, rental income or returns. Property values and income can fall; capital is at risk.

Start with your objective.

How we handle your information

GOV.UK — How to buy a home